
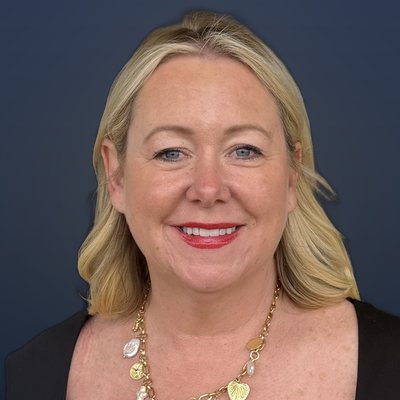
Lois Holder
Founder and DirectorLois has spent years working with self-employed clients, from sole traders to company directors. She knows how each lender looks at self-employed figures and how to present them in the best way.
Book a call with LoisSole traders, directors and contractors
Our self-employed mortgage broker service presents your application to a lender that understands how your income works. Self-employed mortgages are often more straightforward than people expect. The lender you choose can change how much you could borrow, so we compare the whole market to find the one whose criteria suit the way you earn.
Free, no-obligation call · No impact on your credit file
It depends on how you trade. A sole trader, a limited company director and a contractor can earn the same amount and still be assessed in completely different ways. Choose the one that fits you to see what lenders use and the documents they usually ask for.
That's your turnover minus your business expenses, as shown on your tax calculation. An average of your last two years is common. Some will use your latest year on its own if your profit has gone up, while a fall in profit usually means the lower figure is used.
Documents lenders usually ask forBecause this profit has gone up, a lender that uses the latest year would work from a higher income figure.
The usual approach is salary plus dividends from your last two years. Some lenders use your salary plus your share of the company's net profit instead, which can give a higher figure if you leave money in the business. Owning 20% to 25% or more of the company usually means you're treated as self-employed.
Documents lenders usually ask forSame director, same year. The lender's method changes the income figure.
Many lenders base your income on your day rate rather than your accounts. They multiply it by 5 days a week and then by 46 or 48 weeks a year. You'll usually need a current contract and around 12 months' contracting history, although some lenders accept less if you've worked in the same field before.
Documents lenders usually ask forA day rate assessment can show a higher income than your accounts, especially if you pay yourself through a limited company.
Some lenders treat CIS subcontractors much like employees and use your gross pay before CIS tax is deducted, based on your CIS statements or payslips. Others treat you as self-employed and use the net profit from your tax calculations. Lenders using gross pay usually want around 12 months of CIS history and may average your earnings.
Documents lenders usually ask forSame worker, two methods. Finding a lender that uses gross pay can make a real difference.
Your share of the partnership or LLP's net profit is used, usually averaged over the last two years. This comes from your personal tax calculations and the partnership accounts. It's your share that counts, not the total profit of the business, so lenders will check your profit share in the accounts.
Documents lenders usually ask forLenders work from your share of the profit, averaged over two years where they can.
Every lender has its own rules, and which one suits you depends on how you're paid. We'll look at your figures and show you which lenders would use them in your favour.
You can get a mortgage with just one year's accounts, depending on the rest of your circumstances, and there are still plenty of lenders to choose from. Two years is the most common requirement and gives a wider choice of rates, and three years can open up more lenders again.
| Trading history | Choice of lenders | Income figure usually used | Good to know |
|---|---|---|---|
| 1 year | Smaller but solidFewer lenders than with two years, but still plenty of options across the market | Your net profit, or salary and dividends, from that one year | A great starting point, depending on the rest of your circumstances |
| 2 years The usual standard |
Most lendersThe widest choice of rates | An average of both years, or the latest year if your income has gone up | The standard most lenders work to, with the same rates as employed borrowers |
| 3 years or more | Every lenderEvery lender that considers self-employed income | An average of two or three years, or the latest year | A three-year average can help smooth out one weaker year |
Just finished your first year? Once your first tax return has been filed and processed, you may already have enough to apply. Before you apply anywhere, talk to us and we'll tell you which lenders would consider your figures.
Lenders typically average your last two years, some use your latest year if it's higher, and many contractor lenders work from your day rate. Pop in your figures to see the income each method gives.
This shows how lenders commonly read income, not how much you could borrow. We'll go through the real numbers and the lenders that suit you on your free call.
Your income has gone up, so a lender that uses your latest year could work from £3,000 more.
Most day rate lenders assume 5 days a week, even if you work fewer. Some will use the days in your contract instead.
A rough guide only. Lenders' criteria vary, and how much you can borrow depends on your income, outgoings, credit profile and deposit.
Here are a few simple steps to help you present your application in the best possible way, so it goes through as smoothly as possible.
In my experience, it usually comes down to how the application is packaged. Self-employed clients often apply to a lender whose criteria don’t suit the way they earn, and that changes how the lender views their income.
One client I helped was a landscape gardener working as a sole trader, with one year’s accounts, buying his first home. Placed with a lender that works with one year’s figures, the application went through smoothly. A number of lenders will consider one year’s accounts, depending on the rest of your circumstances.
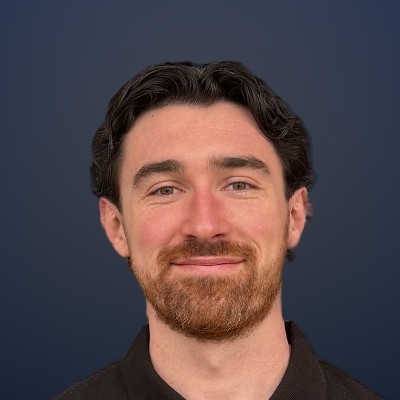
Harry Mansell, CeMAPMortgage Specialist, Keyholder Mortgages
Based on real client cases, with personal details withheld. What’s possible depends on your circumstances and each lender’s criteria.
Harry and Lois both help self-employed clients. Before anything goes near an application, they'll show you how different lenders would read your figures and which ones suit you best.
Lois has spent years working with self-employed clients, from sole traders to company directors. She knows how each lender looks at self-employed figures and how to present them in the best way.
Book a call with LoisHarry works with sole traders, limited company directors, contractors and CIS workers, including people whose income looks lower on paper than it really is. He'll find the lenders whose criteria fit the way you earn.
Book a call with HarryEvery review below was left on Google by a client we've helped, from first-time buyers getting their keys to people who'd been turned down elsewhere.
Common questions from sole traders, directors and contractors. If yours is missing, we can answer it on a free call. Our self-employed mortgage guide goes into more detail, and self-employed first-time buyers can also see our first-time buyer mortgage broker page.
Yes. Most UK lenders offer mortgages to self-employed people, with some accepting just one year of accounts or tax calculations. Lenders work out your income differently depending on whether you're a sole trader, a limited company director or a contractor, so choosing the right lender matters as much as your figures.
You can get a mortgage with one year's accounts, depending on the rest of your circumstances, although most lenders prefer to see two. Two years gives you the widest choice of rates, and with three years every lender that accepts self-employed income is open to you.
Yes. Plenty of lenders will consider one full year of trading, using your net profit, or salary and dividends, from that year. It's fewer lenders than with two years, but there are still lots of options across the market, and we'll show you which ones suit your figures.
Sole traders are assessed on net profit, usually averaged over two years. Limited company directors are assessed on salary plus dividends, or with some lenders salary plus their share of the company's net profit. Contractors are often assessed on their day rate, and CIS workers on either gross pay or net profit, depending on the lender.
Yes, with some lenders. Instead of salary plus dividends, they use your salary plus your share of the company's net profit, which can give a higher income figure if you leave money in the business. This generally applies if you own at least 20% to 25% of the company, and the lender will want to see your company accounts.
Yes. Many lenders assess contractors on their day rate, multiplying it by 5 days a week and 46 or 48 weeks a year. For example, a £450 day rate over 46 weeks gives an income of £103,500. A current contract and around 12 months' contracting history are normally needed, though some lenders accept less.
Yes. Some lenders use your gross pay before CIS tax is deducted, based on your CIS statements or payslips, usually with around 12 months' history. Others use the net profit from your tax calculations, so lender choice can make a real difference to the income figure used.
Expect to be asked for tax calculations (SA302s) and matching tax year overviews, plus recent bank statements, photo ID and proof of your deposit. Limited company directors may also need company accounts, and contractors their current contract. We'll give you a clear list for your situation before you apply.
Yes, you can. If your income has fallen, most lenders will use your latest year rather than an average. If the dip was down to a one-off reason, such as illness or investing in the business, some lenders will take that into account, so tell us up front and we'll find the lenders most likely to understand it.
No. Self-employed borrowers can access the same deposit levels as everyone else, with mortgages available from a 5% deposit. As long as you meet the lender's criteria, being self-employed doesn't change the deposit you need or the rate you're offered.
Choose who you'd like to speak to, then pick a time that suits you. We'll call at the time you book, listen to what you need and talk you through your options.
Prefer to talk now? Call 01787 209880 or email [email protected]
Book a free, no-obligation call with Lois or Harry and find out what's possible for you.