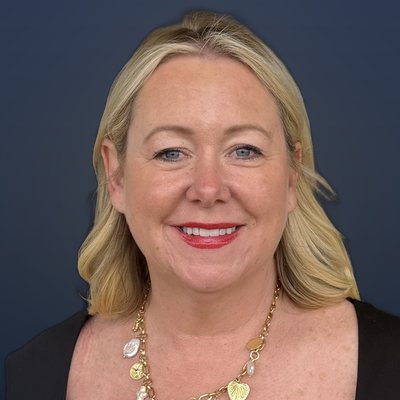
Lois Holder
Founder and DirectorWith years of experience behind her, Lois helps homeowners find their next deal, comparing what their lender offers against the whole market so they can choose with confidence.
Book a call with LoisRemortgages and product transfers
A remortgage broker helps you choose your next deal before the current one ends. Remortgaging means moving your mortgage onto a new deal, either with your current lender or a new one, and you can usually secure a new rate up to six months before your current deal ends. We'll put your lender's offer side by side with the rest of the market before your deal runs out.
Free, no-obligation call · No impact on your credit file
A guide only. Your options depend on your circumstances, credit profile and an up-to-date property valuation.
Start around six months before your current deal ends. Many lenders let you secure a new rate up to six months in advance, so your new deal is ready to start the day your old one finishes. A product transfer can often be arranged in days, while switching lender typically takes 4 to 8 weeks.
We review your current deal, your plans and your loan to value, and check what your lender is offering.
We compare your lender's offer with the rest of the market. Once a rate is held, a rise before it starts may not affect you, depending on the lender.
Your mortgage offer is issued and, if you're switching lender, the legal work is completed. We chase everything for you.
Your new deal begins as your old one ends, with no time spent on your lender's standard variable rate.
Already on your lender's standard variable rate? Remortgaging straight away is usually possible, and in most cases there are no early repayment charges to leave an SVR.
There are three main ways to move onto a new deal. A product transfer keeps you with your current lender, a remortgage moves you to a new lender, and a further advance lets you borrow more from your existing lender. Which one suits you depends on the rates available, your plans and whether you need to raise money.
| Product transferStay with your current lender | RemortgageSwitch to a new lender | Further advanceBorrow more from your lender | |
|---|---|---|---|
| What it is | A new deal with your current lender when your existing one ends. | Moving your mortgage to a different lender with a better deal for you. | Extra borrowing from your current lender, alongside your existing mortgage. |
| Legal work | Usually none needed. | Needed, but many lenders offer free legal work as part of the deal. | Not always needed, depending on the lender. |
| Typical timescale | Often a few days to two weeks. | Typically 4 to 8 weeks. | Typically 2 to 4 weeks. |
| Raising extra money | Not usually, unless combined with a further advance. | Yes, subject to affordability and loan to value. | Yes, that's what it's for. |
| Often best for | When your lender's new rate is competitive and nothing else needs to change. | Better rates elsewhere, raising money, or changing your term or who's on the mortgage. | Borrowing more without leaving a deal you're happy with. |
We look at what your current lender is offering and compare it with the whole market, so you can choose with confidence.
Most people remortgage because their deal is ending, but it can also help you lower your payments, raise money or make a big change. Whatever the reason, we'll talk it through and show you the options that fit.
Move onto a new rate before your fixed or tracker deal finishes, rather than rolling onto your lender's standard variable rate.
A better rate, or a change to your mortgage term, could reduce what you pay each month. Extending your term means paying more interest overall.
Raise money for an extension, a new kitchen or other work on your home, subject to affordability and your loan to value.
Bring other borrowing into one monthly payment. We'll always look at whether it's genuinely the right move for you.
Think carefully before securing other debts against your home. It may cost more overall, and your home may be repossessed if you do not keep up repayments.
Take over the mortgage after a separation, or buy out a family member, with a transfer of equity. Lenders will check you can afford it on your own.
Gone self-employed, become a company director or changed jobs? We know which lenders work with complex income. Self-employed mortgages
Missed payments or other issues since you took out your mortgage don't have to leave you stuck. Remortgaging with bad credit
Approaching retirement or past it? Options like retirement interest-only mortgages and equity release could help. Equity release
We contact every client around six months before their deal ends. That gives us time to secure a new rate early, which can protect you if rates rise before your current deal finishes. If rates fall before your new deal starts, most lenders will let you switch to the lower rate.
Go straight to your bank and you’ll only see that bank’s rates. We compare lenders across the market and look for one that fits your situation, whether that’s staying put or moving.
Lois Holder, CeMAPFounder and Director, Keyholder Mortgages
Based on real client cases, with personal details withheld. What’s possible depends on your circumstances and each lender’s criteria.
We get in touch with every client around six months before their deal ends, so you're never left on your lender's standard variable rate. You'll speak to the same people every time, not a call centre.
With years of experience behind her, Lois helps homeowners find their next deal, comparing what their lender offers against the whole market so they can choose with confidence.
Book a call with LoisHarry specialises in the remortgages that aren't straightforward, from self-employed and complex income to credit issues, raising money and buying out a partner.
Book a call with HarryEvery review below was left on Google by a client we've helped, from first-time buyers getting their keys to people who'd been turned down elsewhere.
Remortgaging, product transfers and raising money: the questions we hear most. Ask us anything else on a free call. Our remortgage guide covers the process in full, and it's also a good time to review your mortgage protection insurance.
A remortgage is when you move your existing mortgage onto a new deal, either with a different lender or with your current one through a product transfer. Most people remortgage when their fixed or tracker deal ends, to avoid moving onto their lender's standard variable rate, but you can also remortgage to raise money or change your mortgage.
Start around six months before your current deal ends. Many lenders let you secure a new rate up to six months in advance, and your new deal can start the day after your old one finishes. We get in touch with our clients around six months before their deal ends.
Switching to a new lender typically takes 4 to 8 weeks, because it involves a full application, a valuation and legal work. Staying with your current lender through a product transfer is usually much quicker, often a few days to two weeks.
It depends on the rates available and your plans. Staying with your lender is often quicker and simpler, while switching can widen your choice of rates or let you raise money. Our job is to set your lender's offer against the rest of the market so you can choose.
If you leave your mortgage during a fixed or discounted period, you will usually pay an early repayment charge, often between 1% and 5% of the balance. Once your deal has ended, or if you are on your lender's standard variable rate, there is usually no charge to move.
Yes, you can usually raise extra money when you remortgage, for example for home improvements, subject to affordability and your loan to value. Another route is a further advance from your current lender. Borrowing more means your mortgage will cost more overall.
Loan to value (LTV) is your mortgage balance as a percentage of your property's value. For example, a £160,000 mortgage on a £250,000 home is a 64% LTV. Lenders look at your LTV alongside your income and credit profile when deciding which deals are available to you.
Yes. You may be able to stay with your current lender on a new deal, or to switch to a lender whose criteria fit your credit history. What's possible depends on the type of credit issue, how recent it is and your overall profile.
Yes. A transfer of equity lets you take over the mortgage in your sole name, and you can raise extra money to buy out your ex-partner's share. Lenders will need to see that you can afford the mortgage on your own income.
Costs can include a lender product fee, a valuation fee and legal fees, although many remortgage deals come with a free valuation and free legal work. A fee for our advice could be charged depending on your individual situation, and we'll always explain any costs before you go ahead.
Choose who you'd like to speak to, then pick a time that suits you. We'll call at the time you book, listen to what you need and talk you through your options.
Prefer to talk now? Call 01787 209880 or email [email protected]
Book a free, no-obligation call with Lois or Harry and find out what's possible for you.