Moving home

Home mover mortgages, timed around your next move.

Home mover mortgages give you several options: porting your mortgage, switching to a new lender or taking out further borrowing. We'll compare them for your situation and work with your estate agent and solicitor, so your sale and purchase line up.

Free, no-obligation call · No impact on your credit file

Three ways to finance your move
Your options

Can you take your mortgage with you when you move?

Usually, yes. Most mortgages are portable, which means you can move your current deal to your new home. Porting isn't always the only option, so we'll compare it against switching to a new lender and help you choose what suits your situation.

01

Port your mortgage

Keep your current deal
How it works

You move your existing mortgage from your current home to your new one. You keep your current rate on the part of the mortgage you bring across, and anything extra you borrow goes onto a rate available at the time. Your lender will still check your affordability and value the new property.

Good to know
  • You keep your rate on the amount you bring across
  • It saves you paying early repayment charges
  • Extra borrowing goes onto a current rate
  • Your lender must approve the new property and your circumstances
02

Switch lender

A fresh mortgage
How it works

You repay your current mortgage when you sell and take out a new one with a different lender for your next home. It can open up better rates, a different term or a lender whose criteria suit you better.

Good to know
  • Early repayment charges may apply if you're still in a deal
  • It can work well if your current deal is ending soon
  • The whole market is open to you
03

Borrow more

Moving up the ladder
How it works

If your next home costs more, you can port your current mortgage and borrow extra on top, or take out one larger mortgage with a new lender. Either way, lenders check you can afford the total borrowing.

Good to know
  • Lenders base it on your current income and outgoings
  • Equity from your sale becomes your deposit
  • We compare the blended cost against a single new mortgage
Can you time your move for when your deal ends?

If you wait until your early repayment charge period has ended, you can move without paying an early repayment charge, and you're free to choose from the whole market. We'll check your dates and help you plan the timing.

Not sure which is right for you? We'll look at your current deal, any early repayment charges and the whole market, then show you the options side by side.

Your equity

How much could you put towards your next home?

The equity in your current home is the difference between what it's worth and what's left on your mortgage. When you sell, it usually becomes the deposit for your next home.

Enter a few rough figures to see your equity, the mortgage you'd need for your next home and its loan to value. We'll go through the real numbers with you on your free call.

£
£
£
Your equity£150,000
Mortgage needed£250,000
Loan to value62.5%
Talk through my numbers
Buying and selling together

How do you sell and buy at the same time?

Most home movers sell and buy at the same time, so both sides complete on the same day. We get your mortgage offer in place quickly and keep in touch with your estate agent and solicitor, so your mortgage never holds up the chain. We work with solicitors and can point you in the right direction for one who can handle both your sale and purchase. From accepting an offer to moving day often takes around 12 to 16 weeks.

Your sale
Step 1Get your home valuedFind out what your home could sell for and what equity you'll have.
Step 2Accept an offerChoose a buyer and agree the sale price.
Step 3Solicitors get to workWe can point you towards a solicitor who can handle both your sale and purchase.
Both sidesExchange contractsYour sale and purchase become legally binding, and a moving date is set.
Moving dayCompletionYou sell, buy and collect the keys to your new home on the same day.
Your purchase
Step 1Agreement in principleWe confirm what you could borrow, usually within 24 hours.
Step 2Find your next homeMake an offer with your budget and mortgage options confirmed.
Step 3Mortgage application and offerWe submit your application and chase the lender for your offer.

Steps we handle for youTimescales vary, and longer chains can take more time.

Want to buy before you sell, or keep your current home? Options such as bridging finance or let to buy can help in the right situation. We'll talk you through whether they could work for you.

Who you'll speak to

Moving home, made simpler.

Whether it's your second home or your fifth, you'll speak to the same people throughout your move, and we'll keep in touch with your estate agent and solicitor so you always know where things stand.

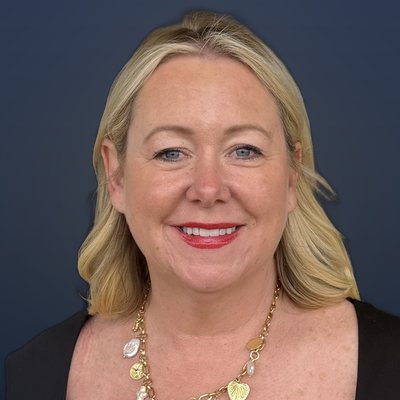
Lois Holder

Founder and Director
  • Founder
  • CeMAP qualified

Home movers are a big part of Lois's work. Having guided clients through many moves over the years, she knows how to line up a sale and purchase and keep the chain moving. It's something she does day in, day out.

Book a call with Lois

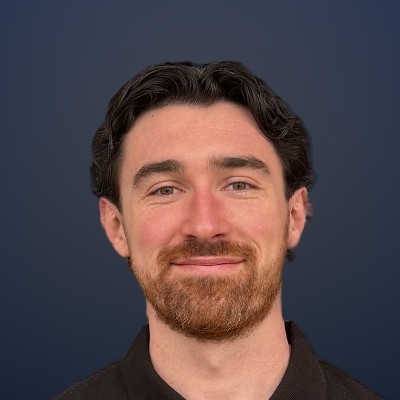
Harry Mansell

Mortgage Specialist
  • Mortgage and protection specialist
  • CeMAP qualified

Harry helps home movers looking to upsize or downsize, from self-employed clients to those who need a little extra help because of past credit issues. Whatever your move, Harry has it covered.

Book a call with Harry
Google reviews

Hear from the people we've helped.

Five-star rated on Google

Every review below was left on Google by a client we've helped, from first-time buyers getting their keys to people who'd been turned down elsewhere.

Home mover FAQs

Your moving questions, answered.

Porting, borrowing more and buying and selling at the same time, answered. For anything else, just ring us. Buying before you sell? See our bridging loan broker page. Taking on a bigger mortgage is also a good time to look at mortgage protection insurance.

What is porting a mortgage?

Porting means moving your existing mortgage from your current home to your new one. Your current rate stays on the part you bring across, and any extra borrowing goes onto a rate available at the time. It can avoid early repayment charges, although your lender will still reassess your circumstances and the new property.

Can I take my mortgage with me when I move?

Usually, yes. Most mortgages are portable, which means you can move your current deal to your new home. The lender still checks your affordability and values the new property, so porting isn't guaranteed. We'll compare it with switching to a new lender so you can compare before deciding.

Will I pay an early repayment charge if I move home?

Repaying your mortgage during a fixed or discounted period usually means paying an early repayment charge. Porting your mortgage can avoid this. Once that period ends, you can move without the charge and choose from the whole market.

Can I borrow more when I move home?

Yes. You can usually borrow more by porting your mortgage and adding extra borrowing, or by taking out a larger mortgage with a new lender. Lenders base this on your current income and outgoings, so as long as you can afford the total borrowing, borrowing more is usually possible.

How much deposit do I need to move home?

Equity from your current home usually becomes your deposit, so in many cases no extra savings are needed. Most lenders need a deposit of at least 5% to 10% of your next home's value, and your equity often covers this and more.

Should I sell my home before I buy?

Most people sell and buy at the same time so both complete on the same day. Having a buyer for your home before you offer on your next one can make you a stronger buyer. If you want to buy first, options like bridging finance may help in some situations.

How long does it take to move home?

From accepting an offer to moving day often takes around 12 to 16 weeks, although longer chains can take more time. Getting your agreement in principle and mortgage application moving early helps make sure your mortgage doesn't hold anything up.

What costs are involved in moving home?

Moving home costs can include stamp duty, two sets of legal fees for your sale and your purchase, estate agent fees, a survey, mortgage product and valuation fees, and removals. You may also pay an early repayment charge if you leave your current mortgage during a fixed deal.

Can I move home with bad credit?

Yes. If your credit has changed since you took out your mortgage, there can be options to port with your current lender or switch to a lender whose criteria fit. Much comes down to the type of credit issue, how recent it is and your overall profile.

Book a free call

Let's talk about your plans.

Choose who you'd like to speak to, then pick a time that suits you. We'll call at the time you book, listen to what you need and talk you through your options.

  • Completely free, with no obligation
  • Speak to Lois or Harry directly, not a call centre
  • Advising clients in Suffolk, Essex and across the UK
Who would you like to speak to?

Prefer to talk now? Call 01787 209880 or email [email protected]

Loading the booking calendar… Or book directly with Lois or Harry

Ready to take the next step?

Book a free, no-obligation call with Lois or Harry and find out what's possible for you.