
Family-run mortgage broker in Sudbury, Suffolk

Mortgages,
the honest way.

Expert advice, real people, no judgement.

Looking for a mortgage broker in Sudbury, Suffolk? From first homes and remortgages to people who've been turned down elsewhere, our advisers will explain your options and search the market for a mortgage that suits you, wherever you are in the UK.

  • Whole-of-market access to lenders
  • 100+ five-star Google reviews
  • Decades of combined experience

Free, no-obligation call · No impact on your credit file

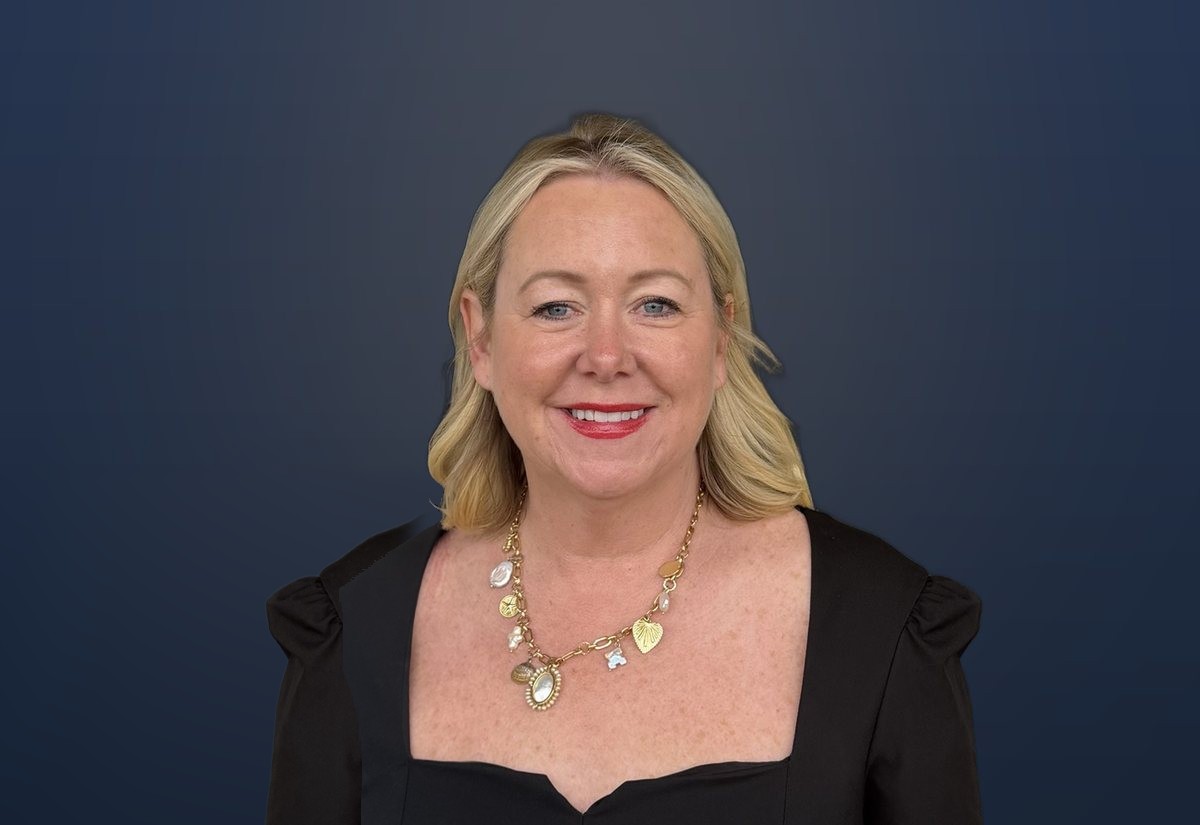
Lois Holder, Founder and Mortgage Specialist at Keyholder Mortgages
Lois HolderFounder and Mortgage Specialist
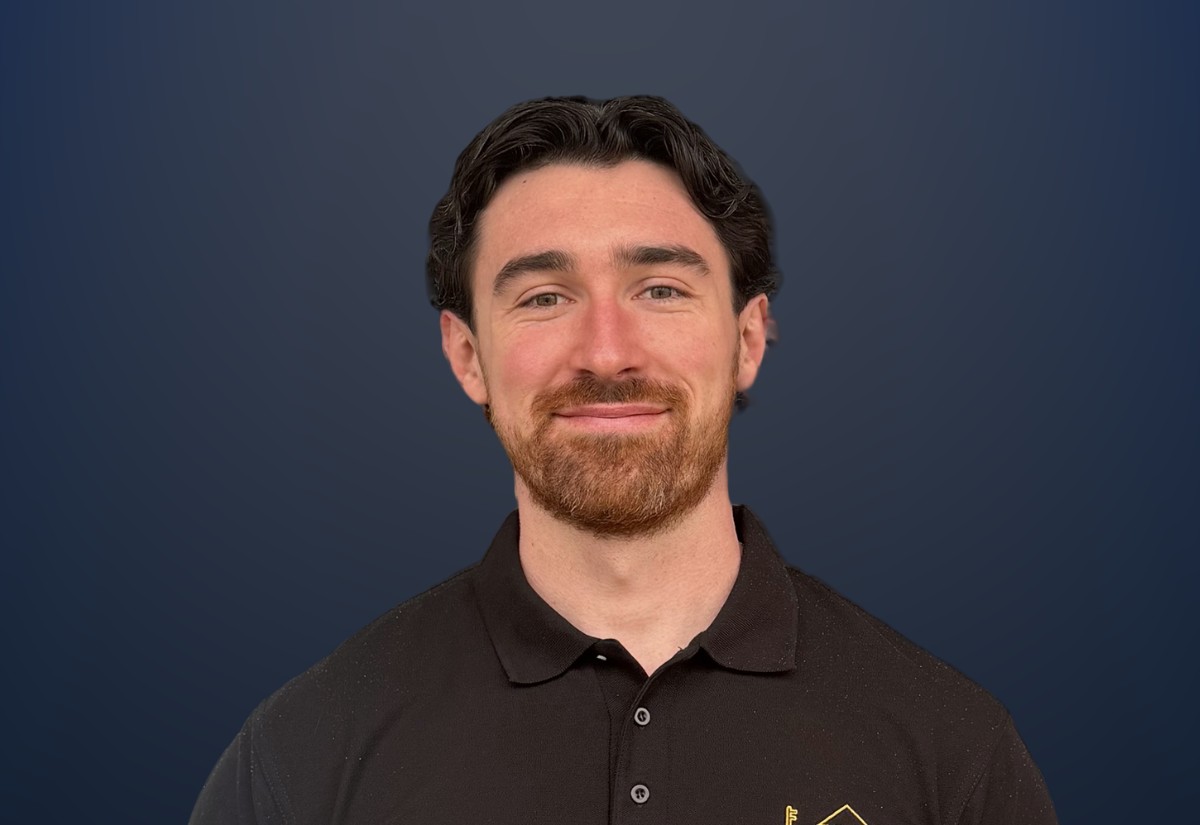
Harry Mansell, Mortgage Specialist at Keyholder Mortgages
Harry MansellMortgage Specialist
100+ five-star reviews Read them on Google
Whole of market access to lenders
Decades of combined experience
FCA regulated via Cutting Edge Mortgages
Who we help

Mortgage advice for every stage, and every story.

No two situations are the same. From first homes to complex income and credit history, we'll look at your full picture and tell you honestly what's possible, whether you're in Sudbury, elsewhere in Suffolk or anywhere in the UK.

First-time buyers

Buying your first home

From working out what you can borrow to getting the keys, we explain each stage clearly and handle the paperwork for you.

  • Low and 0% deposit mortgage options
  • Ways to increase how much you can borrow
  • Guidance from initial meeting all the way to completion
Book a free call
Bad credit

Turned down elsewhere?

Missed payments, defaults or CCJs don't automatically mean no. We'll look at your whole story, not just your score.

  • Defaults, CCJs and missed payments
  • Debt management plans or IVAs
  • Low credit scores
Book a free call

Give us a call or book an appointment to find out exactly how we can help.

How it works

From first call to getting the keys.

Working with a mortgage broker is simpler than most people expect. We do the searching, the paperwork and the chasing, and keep you updated at each stage.

  1. Book a free call

    Have an initial chat with Lois or Harry about your plans and situation. No obligation and completely free: we're here to listen and help.

  2. We search the market

    We compare lenders across the whole market and explain your options so you can choose with confidence.

  3. We handle the application

    We prepare and submit everything, then deal with the lender, your solicitor and the estate agent so you don't have to.

  4. Get your keys

    We keep you updated right through to completion, and we're here when your deal ends to review your options again.

Meet the family

The family behind Keyholder Mortgages.

Family is at the heart of everything we do. Lois founded Keyholder Mortgages in Sudbury, Suffolk, Harry works alongside her, and we look after every client the way we'd look after our own. We've been through the process ourselves too, so we know how daunting it can feel.

That's why our aim is simple: to make getting a mortgage as smooth as possible. From a first home to a more complex situation that needs extra help, we'll listen first, explain everything clearly and help you get the keys to the home you've been dreaming of.

Lois Holder, Founder and Director of Keyholder Mortgages
Founder and Director

Lois Holder

  • Founder
  • CeMAP qualified
  • Home buyers and movers

Lois has been helping people buy homes for decades (we know, she doesn't look it). Nothing makes her happier than seeing dreams come true: a first-time buyer getting the keys, a family moving into their dream home, or a homeowner raising money from their property in good times and bad. Buying your next home? Her knowledge of the whole market is hard to beat.

Away from work: family time, Britain's Got Talent and a cheeky glass of Savvy B.

Book a call with Lois
Harry Mansell, Mortgage Specialist at Keyholder Mortgages
Mortgage Specialist

Harry Mansell

  • Mortgage and protection specialist
  • CeMAP qualified
  • Complex lending specialist

Helping first-time buyers is Harry's bread and butter. Having been a first-time buyer himself, he wants to help as many people as possible find it simple and straightforward. Not to mention, he's our complex lending specialist: bad credit, tricky income or a quirky property type, Harry is there to listen and look for a lender that fits your circumstances.

Away from work: padel, a good steak, Marvel films and Liverpool FC (he promises it won't get in the way of business).

Book a call with Harry
Case studies

Real clients, real results.

A few examples of how we've helped. Every situation is different, but these show what's possible when someone takes the time to look at the full picture.

Bad credit

Moving up the ladder with defaults and CCJs

The situation
Our client had six defaults and two active CCJs. She needed a bigger home so her mum could move in with her.
What we did
We looked at her whole story, not just her credit file, and found a lender willing to look past the credit history.
The result
She moved into her new home, with room for her mum to live with her.
Bad credit mortgages
First-time buyers

Buying a first home with no deposit

The situation
These first-time buyers were ready to buy their own home but had no deposit saved.
What we did
We found a no-deposit mortgage that worked for them, then put protection in place so their new home was covered if the unexpected happened.
The result
They got the keys to their first home, protected from day one.
First-time buyer mortgages
Buy-to-let

Remortgaging a buy-to-let after a recent CCJ

The situation
A landlord needed to remortgage their buy-to-let, but a recent CCJ ruled out most lenders.
What we did
We searched for lenders who would accept a recent CCJ on a buy-to-let remortgage and handled the application from start to finish.
The result
The remortgage completed with a lender comfortable with the CCJ.
Buy-to-let mortgages

Client names withheld to protect their privacy. Outcomes depend on individual circumstances.

Google reviews

Hear from the people we've helped.

Five-star rated on Google

Every review below was left on Google by a client we've helped, from first-time buyers getting their keys to people who'd been turned down elsewhere.

FAQs

Your questions, answered.

The questions we're asked most often. Can't see yours? Give us a call or book a free chat.

See all FAQs →
Rather talk it through?

Speak to Lois or Harry directly. No call centres, no pressure.

01787 209880 [email protected]

Can I buy a house with no deposit?

Yes, it can be possible, but it will depend on your credit profile, your income and the lender's criteria. A small number of lenders offer 0% deposit mortgages for first-time buyers, and help from family, such as a gifted deposit or a family member using their savings or home as security, can open up more options.

Can I get a mortgage with a CCJ?

Yes, depending on the amount, the date the CCJ was registered and whether it has been satisfied. Your overall credit profile and each lender's criteria decide what's available, and we'll look for lenders whose criteria fit your situation.

Can I get a mortgage with missed payments?

Yes, although it depends on how many payments were missed, how recently and what type of credit they were on. Missed mortgage or secured loan payments are looked at more closely, and options vary from lender to lender.

Can I get a mortgage with defaults?

Yes. How many defaults you have, the amounts, when they were registered and whether they have been settled all matter, along with your wider credit profile and the lender's criteria.

How much can I borrow as a first-time buyer?

Most lenders will lend up to 4.5 times your annual income, but some offer products for first-time buyers that allow you to borrow up to 6 times your income if you meet their criteria. The final amount depends on your outgoings, any credit commitments and the size of your deposit. Book a free call and we'll work out what you could realistically borrow.

What documents will I need for my mortgage?

You'll usually need photo ID such as a passport or driving licence, proof of address, your last three months' payslips and bank statements, and your latest P60. If you're self-employed, lenders normally ask for your SA302 tax calculations and tax year overviews for the last two years, although some lenders will accept just one year's accounts. We'll give you a checklist that fits your situation.

How early can I lock in my remortgage?

You can usually secure a new rate up to six months before your current deal ends, and some lenders allow even earlier. If rates fall before your new deal starts, most lenders will let you switch to the lower rate. Speaking to us early gives you time to plan before your current deal ends.

Book a free call

Let's talk about your plans.

Choose who you'd like to speak to, then pick a time that suits you. We'll call at the time you book, listen to what you need and talk you through your options.

  • Completely free, with no obligation
  • Speak to Lois or Harry directly, not a call centre
  • Advising clients in Suffolk, Essex and across the UK
Who would you like to speak to?

Prefer to talk now? Call 01787 209880 or email [email protected]

Loading the booking calendar… Or book directly with Lois or Harry

Ready to take the next step?

Book a free, no-obligation call with Lois or Harry and find out what's possible for you.