Know your budget
We'll work out what you could realistically borrow before you start viewing, so you can house hunt with confidence.
With a first-time buyer mortgage broker on your side, you don't have to work it all out alone. We'll show you how much you could borrow, search for a mortgage across the market and guide you through every stage, from your first call to getting the keys.
Free, no-obligation call · No impact on your credit file
Not sure where you stand? Call 01787 209880 and we'll tell you honestly.
A first-time buyer mortgage is a home loan for someone who has never owned a property before. Many lenders offer first-time buyers lower deposit options, higher borrowing and extra support, and in England and Northern Ireland you may pay less stamp duty too.
The hard part is knowing which lender suits you. Each one has different rules on deposits, income and credit history. We compare the market, explain your options clearly and handle the application for you, so you can focus on finding the right home.
We'll work out what you could realistically borrow before you start viewing, so you can house hunt with confidence.
We search the whole market, including lenders you won't find on comparison sites, to match you with a suitable deal.
From your agreement in principle to your mortgage offer, we deal with the lender and keep everything moving.
Once you're buying, we'll talk you through protection so your home is covered if the unexpected happens.
There's more than one way to buy your first home. These are the options we use most often with first-time buyers, and we'll help you work out which suits you best.
Lending up to 95% of the property price is common, so a 5% deposit can be enough to get started. A bigger deposit can give you a wider choice of rates.
A small number of lenders offer first-time buyers a 0% deposit mortgage, so you can buy without saving a deposit first. Your income, credit profile and the lender's criteria decide whether it's an option.
If you've paid your rent on time for at least 12 months, some lenders offer a 0% deposit mortgage, as long as your mortgage payment isn't higher than your rent.
Parents, grandparents or other relatives can gift you some or all of your deposit. Lenders will need a signed gift letter, and we'll guide you through it.
Options such as joint borrower, sole proprietor mortgages let a family member's income count towards your borrowing without them owning the home.
Lending is often around 4.5 times income, and some first-time buyer products go up to 6 times, depending on your overall profile.
These first-time buyers were ready to buy but had no deposit saved. We found them a 0% deposit mortgage, put protection in place and they got the keys to their first home.
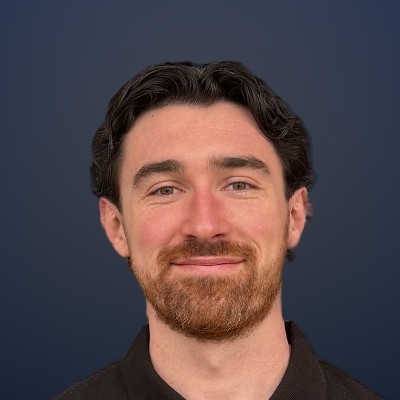
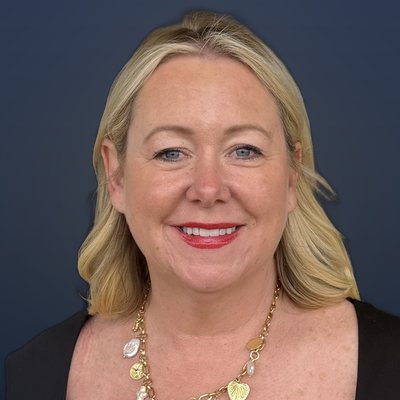
As a first-time buyer, you could borrow more than you think. Most lenders lend around 4.5 times your income, but you could borrow up to 6 times your income, depending on your overall profile. Speak to Lois or Harry to find out where you fit.
Exact lending figures depend on your individual circumstances and your overall credit profile.
How your deposit helps: the size of your deposit can affect how much you can borrow. A deposit of 10% or more can help you get closer to 6 times your income, depending on the lender.
Find out where you fitThis is a rough guide only and not a mortgage offer or advice. Exact lending figures depend on your individual circumstances and your overall credit profile.
Most first-time buyers I speak to expect to need a 10% or 20% deposit, and often that isn’t the case. Depending on your circumstances, there are options with a small deposit, and some lenders offer mortgages with no deposit at all. The other surprise is how much they could borrow, as some lenders have schemes that let first-time buyers borrow more.
Family help comes up all the time. It might be a gifted deposit, a family-backed mortgage, or gifted equity when you’re buying a home from a relative. The family member’s own circumstances can play a part in the application too, so we look at the whole picture from the first call.
Harry Mansell, CeMAPMortgage Specialist, Keyholder Mortgages
Based on real client cases, with personal details withheld. What’s possible depends on your circumstances and each lender’s criteria.
Once your offer on a property is accepted, buying your first home usually takes around 8 to 12 weeks. Here's what happens along the way, and we'll keep you updated throughout.
A free call to get to know you, your income, your deposit and your plans, and to answer any questions you have.
We arrange an agreement in principle showing how much a lender is likely to lend, so estate agents know you're serious.
Start viewing with a clear budget. We have tools to help you understand what to offer, and we're on hand whenever you need us.
Once your offer is accepted, we submit your full application and send the lender your documents straight away.
The lender values the property and checks your application, then issues your mortgage offer. We keep things moving and chase on your behalf.
We work with solicitors and can guide you through the legal process, from searches and surveys to exchanging contracts, so you always know what's happening.
The purchase completes and the keys to your first home are yours. Time to celebrate.
Timescales are a rough guide from your offer being accepted. Every purchase is different, and things like chains, surveys and lender checks can affect how long it takes.
Helping first-time buyers get the keys to their first home is a big part of what we do. Read our Google reviews and you'll see just how many first-time buyers we've helped.
Lois has guided many first-time buyers onto the property ladder. Nothing makes her happier than seeing a first-time buyer get the keys to their new home.
Book a call with LoisFirst-time buyers are Harry's bread and butter. Having been a first-time buyer himself, he knows exactly how it feels and makes the process as simple as he can.
Book a call with HarryEvery review below was left on Google by a client we've helped, from first-time buyers getting their keys to people who'd been turned down elsewhere.
The things first-time buyers ask us most. Got a different question? Call us and we'll talk it through. For more detail, read our first-time buyer mortgage guide, or see our bad credit mortgage broker page if your credit history isn't perfect.
Most lenders ask for at least 5% of the property price, so on a £200,000 home that's £10,000. A few lenders also offer 0% deposit mortgages, and a bigger deposit can widen your choice of products.
Yes. A few lenders offer 0% deposit mortgages for first-time buyers, including track record mortgages for renters who have paid their rent on time for at least 12 months. Your income, credit profile and the lender's criteria all play a part, and help from family can open up more options.
A typical starting point is around 4.5 times your yearly income, and some lenders go up to 6 times for first-time buyers who meet their criteria. Book a free call and we'll work out where you fit.
First-time buyers in England and Northern Ireland get stamp duty relief, so they pay less, or nothing at all, on homes up to a set price. The thresholds are set by the government and can change, so we'll check the current rates with you when you buy.
Yes. Family can gift you some or all of your deposit, which lenders accept with a signed gift letter. Some lenders also offer family-backed mortgages, where a relative's income, savings or home helps you borrow more without them owning the property.
Yes, in many cases, depending on the type of credit issue, how recent it was and whether it's been settled. Certain lenders focus on helping people with defaults, CCJs or missed payments, and complex cases like these are Harry's speciality.
Yes. Self-employed buyers usually need two years of accounts or tax calculations, although some lenders accept one year. If you've just started a new job, some lenders will consider you from your first day, especially if you've stayed in the same line of work.
Many lenders use a soft credit search for an agreement in principle, which doesn't affect your credit score. Some use a hard search, so we'll tell you which type a lender uses before we apply.
Choose who you'd like to speak to, then pick a time that suits you. We'll call at the time you book, listen to what you need and talk you through your options.
Prefer to talk now? Call 01787 209880 or email [email protected]
Book a free, no-obligation call with Lois or Harry and find out what's possible for you.