Limited company landlords

Limited company buy-to-let mortgages, without the guesswork.

Limited company buy-to-let mortgages let you buy rental property through a company, usually a special purpose vehicle (SPV) set up just to hold property, which your accountant can help you set up. We've helped plenty of clients grow their portfolios through a limited company, buying multiple properties, and we're just as happy to help if you're buying just the one. Either way, we compare the whole market to find the lender whose criteria suit your company and your plans.

Free, no-obligation call · First company purchases and growing portfolios

Lender criteria

What do lenders look for in a limited company?

Lenders look at both the company and the people behind it. They want a company set up to hold property with the right SIC code, rent that comfortably covers the mortgage, and directors who meet their criteria. These are the six things that matter most, although every lender sets its own rules.

SPV Company type

A company set up to hold property

Lenders generally prefer a special purpose vehicle, a company whose only business is buying and letting property. Some lenders will also lend to trading companies, but the choice of lenders is smaller.

Depends on the individual lender and how your company is set up.
4 SIC codes

A property SIC code

Lenders usually want your company registered with one of these SIC codes. If yours has a different code, it can usually be updated with Companies House.

68100682016820968320
Each lender sets its own rules on SIC codes.
20% to 25% Deposit

Typically up to 75% or 80% loan to value

Most lenders lend up to 75% or 80% of the property's value, so you'll usually need a deposit of 20% to 25%, plus enough for fees and buying costs.

Exact limits vary by lender and how your company is set up.
125% Rental cover

Rent that covers the mortgage, plus headroom

The rent usually needs to be at least 125% of the monthly mortgage payment, worked out at the lender's test rate rather than the rate you actually pay.

Rental cover and test rates differ from one lender to another.
Portfolio Multiple properties

Room to grow your portfolio

You can hold one property or several in the same company. As your portfolio grows, lenders look at it as a whole, so it pays to use lenders whose criteria suit where you're heading.

Portfolio criteria vary between lenders.
Day one New companies

No company accounts needed

A newly formed SPV is usually accepted from the day it's set up, so you don't need any trading history or company accounts, as long as the directors meet the lender's criteria.

Requirements for new companies depend on the lender.
Rental cover check

Will the rent cover the mortgage?

For limited company buy-to-let, most lenders want the monthly rent to be at least 125% of the mortgage payment. They work out the payment at a test rate, which is usually higher than the rate you'll actually pay, so the rent still covers it if rates rise.

  1. Enter the loan and the rent. Use the amount you'd borrow and the monthly rent you expect.
  2. Check the test rate. We've used 5.5% as an example. Each lender sets its own, and longer fixed rates are often tested lower.
  3. See if it passes. We'll work out the real figures across the market on your free call.
Quick check
£
£
%
Monthly payment at the test rate (interest only)£688
Rent needed at 125%£859
ResultThe rent covers itYour rent is £91 a month above what most lenders need at this test rate.
Check my figures with an adviser
Step by step

How do you buy a property through a limited company?

Set up your company, get an agreement in principle, then apply in the company's name once you've found the property. Your solicitor handles the legal work through to completion, and we handle the mortgage side from start to finish.

  1. Speak to your accountantWhether to buy through a company depends on your wider circumstances, so it's a decision to make with your accountant. Once you've decided, we'll take care of the mortgage.
  2. Set up your companyRegister an SPV with Companies House using a property SIC code. Your accountant can do this for you, and it doesn't take long.
  3. Get an agreement in principleWe'll check the directors' details and find the lenders that suit your plans, so you know your budget before you make an offer.We handle this
  4. Find your property and applyWe submit the application in the company's name, arrange the valuation and keep things moving with the lender.We handle this
  5. Legal work beginsFrom here, the solicitor takes care of everything until completion. This often takes around 8 to 12 weeks, depending on the purchase and the lender.
  6. CompleteThe purchase completes and your company owns the property.

Already own the property in your own name? There are lots of different ways to move a property into a company. The company may have to buy it from you, potentially with a new mortgage. This can have costs and tax implications, so speak to your accountant before you do anything, as we can't advise on tax. We can only arrange the mortgage for you.

From experience

Where new limited company landlords trip up

The most common problem I see is the company setup. Sometimes it’s registered with the wrong SIC code. Sometimes the company is layered, meaning it’s owned by another company, without the landlord realising, and not all lenders accept layered structures.

It’s far easier to get this right before you buy than to fix it afterwards. Speak to us and your accountant before you set the company up, and we’ll check it fits the lenders you’re likely to use.

Harry Mansell, CeMAPMortgage Specialist, Keyholder Mortgages

Based on real client cases, with personal details withheld. What’s possible depends on your circumstances and each lender’s criteria.

Who you'll speak to

Landlord advice from people who know the criteria.

Harry and Lois both arrange limited company buy-to-let mortgages, from a first company purchase to a growing portfolio. You'll speak to the same person from your first call to completion.

  • Whole-of-market lender search for limited companies
  • New SPVs, multiple directors and growing portfolios
  • We keep in touch with your accountant and solicitor

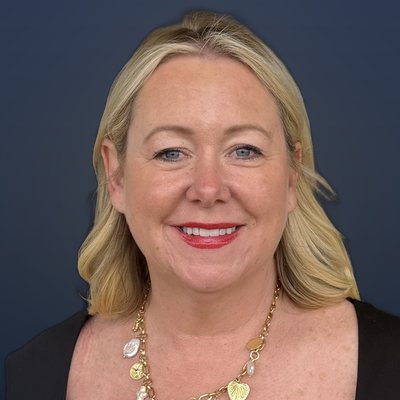
Lois Holder

Founder and Director

Lois helps landlords buying their first property through a company and those adding to an established portfolio, drawing on years of lending knowledge.

Book a call with Lois

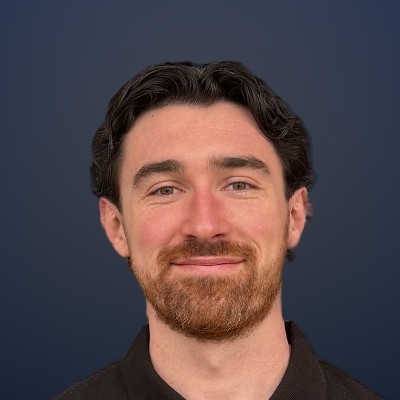
Harry Mansell

Mortgage Specialist

Harry helps landlords set up their first company purchase and grow their portfolios, including structures with several directors or shareholders.

Book a call with Harry
Google reviews

Hear from the people we've helped.

Five-star rated on Google

Every review below was left on Google by a client we've helped, from first-time buyers getting their keys to people who'd been turned down elsewhere.

Limited company buy-to-let FAQs

Your company questions, answered.

What landlords ask us most about buying through a limited company. If your question isn't listed, we're happy to answer it on a call. Our buy-to-let mortgage guide and portfolio landlord mortgage guide go into more detail, and our buy-to-let mortgage broker page covers buying in your own name.

01

Can I get a buy-to-let mortgage through a limited company?

Yes. Most buy-to-let lenders offer mortgages to limited companies, usually a special purpose vehicle (SPV) set up just to hold property. The company takes out the mortgage and owns the property. A deposit of 20% to 25% is typical, although the exact criteria depend on the lender and how your company is set up.

02

Which SIC codes do lenders accept for a limited company buy-to-let?

Your company will usually need a property SIC code, usually 68100, 68201, 68209 or 68320, which cover buying, selling, letting and managing property. The codes each lender accepts can vary, and if your company has a different code, it can usually be updated with Companies House.

03

How much deposit do I need for a limited company buy-to-let mortgage?

Usually 20% to 25%, as limited company lending tends to go up to 75% or 80% of the property's value, depending on the lender and your individual circumstances. You'll also need money for fees, legal costs and buying costs, and a larger deposit can widen your choice of lenders and rates.

04

Can I buy multiple properties in a limited company?

Yes, you can. Many landlords hold several properties in the same company and add to it over time. As your portfolio grows, lenders look at it as a whole, so the lenders available to you depend on their criteria and your company's set-up. We'll find the ones that suit where you're heading.

05

Can a newly formed company get a buy-to-let mortgage?

Yes. Many lenders accept a newly formed SPV from the day it's set up, so you don't need any trading history or company accounts. The lender assesses the directors instead, looking at things like their credit history and any other properties they own, and each lender's criteria are slightly different.

06

How much rent do I need for a limited company buy-to-let mortgage?

Usually at least 125% of the mortgage payment, worked out at a test rate set by the lender. For example, on a £150,000 interest-only loan tested at 5.5%, the payment is about £688 a month, so the rent would need to be around £859. Test rates and rental cover depend on the lender.

07

Can first-time landlords buy through a limited company?

Yes. A number of lenders accept first-time landlords buying through a limited company, depending on the lender and your individual circumstances. Some lenders prefer you to own your own home, so we'll match you with the lenders whose criteria suit your situation.

08

Can I move my existing buy-to-let into a limited company?

Yes, but there are lots of different ways to do it. One common route is for the company to buy the property from you, potentially with a new mortgage. There can be costs and tax implications, so take advice from your accountant first, as tax is outside what we advise on. We can arrange the company's mortgage.

09

Are limited company buy-to-let mortgage rates higher?

They can be slightly higher than personal-name buy-to-let rates, depending on the lender and your individual circumstances, and fees can be higher too. The difference is often small, and we compare the whole market to find the lender with the right balance of rate, fees and criteria for your company.

10

Should I buy in my own name or through a limited company?

That's a decision to make with your accountant, as it depends on your income, your plans and your wider circumstances. We arrange both personal-name and limited company buy-to-let mortgages and can show you how lenders would treat each option.

Book a free call

Let's talk about your plans.

Choose who you'd like to speak to, then pick a time that suits you. We'll call at the time you book, listen to what you need and talk you through your options.

  • Completely free, with no obligation
  • Speak to Lois or Harry directly, not a call centre
  • Advising clients in Suffolk, Essex and across the UK
Who would you like to speak to?

Prefer to talk now? Call 01787 209880 or email [email protected]

Loading the booking calendar… Or book directly with Lois or Harry

Ready to take the next step?

Book a free, no-obligation call with Lois or Harry and find out what's possible for you.