
Life, illness and income cover

Mortgage protection insurance for your family, income and home.

Mortgage protection insurance can help protect your home if life doesn't go to plan. Arranging your mortgage is only half the job, because we want you to stay in your home, whatever happens. Life insurance, critical illness cover and income protection are there to protect you, the person paying for the house, so you and your family are looked after if the worst were to happen. We search protection providers across the market for cover that suits your situation.

Free, no-obligation call · Cover for you, your family and your business

Types of cover

What types of protection do we advise on?

We advise on all the main types of personal protection, plus private medical insurance for individuals and businesses and home insurance. We compare providers across the market, because each one has different criteria, definitions and prices.

Life insurance

Pays a lump sum if you pass away during the policy term. It can be set up to match your mortgage, reducing as a repayment mortgage goes down, or stay level to leave a set amount for your family.

Good to knowCover can be for one person or two, and the policy can be written in trust so the payout goes to the people you choose.
Critical illness cover

Pays a lump sum if you're diagnosed with a serious illness covered by the policy, such as certain cancers, heart attacks or strokes. The payout could help clear or reduce your mortgage while you focus on recovering.

Good to knowEach provider covers different conditions with different definitions, so comparing them really matters.

Income protection

Income protection protects the money-maker: you. If your income stopped because of illness or injury, how would you pay the bills? It pays you a monthly income, usually a percentage of your earnings, until you're back at work or the policy ends.

Good to knowThis is especially worth considering if you're self-employed and have no sick pay to fall back on.

Private medical insurance

Skip the long waiting lists for tests, specialists and certain types of surgery. Many policies also include a digital GP service, often with same-day appointments when you need them, so you're not waiting weeks to be seen.

Good to knowPre-existing conditions are usually excluded, at least for an initial period.

Private medical for businesses

Cover for company directors and employees, helping your team get treated sooner and back to work faster. Plans can be set up for small teams and growing businesses.

Good to knowAs an employee benefit, it can help you attract and keep good people.

Home insurance

Buildings insurance covers the structure of your home and is usually a condition of your mortgage. Contents insurance covers your belongings. We can arrange both, often together in one policy.

Good to knowIf you're buying, your lender will usually need buildings insurance in place from exchange of contracts.

Cover, exclusions and costs depend on the provider and your individual circumstances.

Compare cover

What's the difference between life insurance, critical illness and income protection?

Life insurance pays out if you pass away, critical illness cover pays out if you're diagnosed with a serious illness, and income protection replaces part of your income if you can't work. Plenty of people combine them, because each one covers a different risk.

  Life insurance Critical illness Income protection
Pays out when You pass away during the policy term You're diagnosed with a serious illness covered by the policy You can't work because of illness or injury
How it pays A lump sum A lump sum A monthly income
Often used to Clear the mortgage and support your family Clear or reduce the mortgage while you recover Keep up with the mortgage and bills each month
Can pay out more than once? No, it pays once Usually once, although some plans allow more Yes, many plans pay for each valid claim

Cover and features depend on the provider and your individual circumstances.

How it works

How does setting up protection work?

It's simpler than most people expect. We talk through what you'd want covered, compare providers across the market, and you answer a short health and lifestyle questionnaire. In a lot of cases, cover can be put in place without a medical.

  1. Free callWe talk about your family, your mortgage and what you'd want covered if the worst happened.
  2. We compare providersWe search providers across the market to compare cover and price for your situation.
  3. Health questionnaireYou answer a short set of health and lifestyle questions. It's important to answer them fully and honestly.
  4. The provider's decisionMost applications are decided quickly. Sometimes the provider asks for a report from your GP.
  5. Cover startsYour policy is in place, and we're here to review it whenever your circumstances change.

Why answering honestly matters

Your health questionnaire is what the provider bases your cover on. If information isn't disclosed accurately, a provider could reduce or decline a claim, which is the last thing your family needs. A pre-existing condition doesn't usually stop you getting cover, it may just change the price or terms, so it's always best to tell us everything.

From experience

The risk most people don’t see

What most clients don’t realise until we talk it through is the risk they take on with a mortgage. If you can’t keep up the payments, missed payments can damage your credit file, which can make borrowing harder in future.

Protection is there to help keep the mortgage paid if you can’t work through illness or injury, or to clear it if the worst happens. Explaining that risk, and how to cover it, is part of our job.

Harry Mansell, CeMAPMortgage Specialist, Keyholder Mortgages

Based on real client cases, with personal details withheld. What’s possible depends on your circumstances and each lender’s criteria.

Who you'll speak to

Protection advice from people you already know.

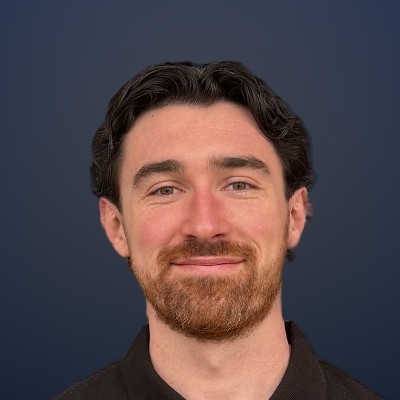
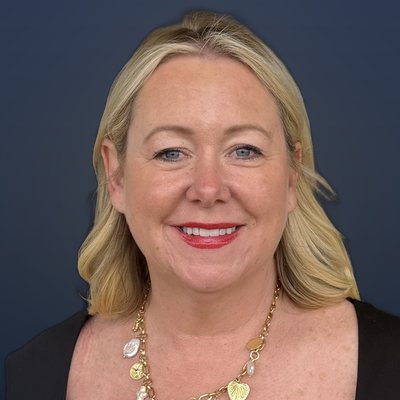
Harry and Lois both advise on every type of protection we offer, so you can sort your mortgage and your cover with the same person, in the same conversation.

Lois Holder

Founder and Director

Protection is one of Lois's real strengths, and she talks it through with every client she helps buy or remortgage. She takes the time to understand your family, your income and what would happen if you couldn't work, then compares cover across a range of providers to help keep your home and the people in it protected.

  • Life insurance
  • Critical illness
  • Income protection
  • Private medical
  • Home insurance
Book a call with Lois

Harry Mansell

Mortgage Specialist

Harry specialises in protection for people whose circumstances aren't straightforward, from first-time buyers protecting their first home to self-employed clients with no sick pay to fall back on. He also helps business owners arrange private medical cover for their team, comparing policies across providers so the cover matches what you actually need.

  • Life insurance
  • Critical illness
  • Income protection
  • Private medical
  • Home insurance
Book a call with Harry
Google reviews

Hear from the people we've helped.

Five-star rated on Google

Every review below was left on Google by a client we've helped, from first-time buyers getting their keys to people who'd been turned down elsewhere.

Protection FAQs

Your protection questions, answered.

Protecting your family, your income and your home: the questions people ask us most. If there's something we haven't covered, get in touch. Buying your first home? See our first-time buyer mortgage broker page. Coming to the end of a deal? See our remortgage broker page.

Life, illness and income cover

Do I need life insurance with a mortgage?

No, it isn't a legal requirement, and most lenders don't insist on it. However, life insurance can pay off or reduce your mortgage if you pass away, so your family isn't left with the repayments. Whether it's right for you depends on your circumstances and who relies on you.

What's the difference between life insurance and critical illness cover?

Life insurance pays out if you pass away during the policy term. Critical illness cover pays out if you're diagnosed with a serious illness covered by the policy, such as certain cancers, heart attacks or strokes. They can be taken separately or combined in one policy, depending on the provider.

What is income protection insurance?

Income protection pays you a monthly income, usually a percentage of your earnings, if you can't work because of illness or injury. Payments start after a waiting period you choose and continue until you return to work or the policy ends. Terms depend on the provider and your occupation.

How much does life insurance cost?

It depends on your age, health, whether you smoke, how much cover you need and for how long. Providers price these differently, which is why we compare the market for cover that suits your needs and budget.

Health questions and applications

Do I have to answer health questions to get protection?

Yes. Most applications include a short health and lifestyle questionnaire, and occasionally the provider asks for a report from your GP. It's important to answer every question fully and honestly, because inaccurate information could lead to a claim being reduced or declined.

Can I get life insurance with a pre-existing medical condition?

Often, yes. Many people with pre-existing conditions can still get cover, although the price may be higher or certain conditions may be excluded. Each provider assesses conditions differently, so the outcome depends on the provider and your individual circumstances.

What does writing a life insurance policy in trust mean?

Writing a policy in trust means the payout goes directly to the people you choose, rather than forming part of your estate. This can help your family receive the money more quickly, without waiting for probate. We'll explain how it works when we set up your cover.

Private medical and home insurance

What is private medical insurance?

Private medical insurance pays for private treatment of eligible conditions, which can help you avoid long waiting lists for tests, specialists and certain types of surgery. Many policies also include a digital GP service, often with same-day appointments. Pre-existing conditions are usually excluded, at least for an initial period, depending on the provider.

Do you arrange private medical insurance for businesses?

Yes. We arrange private medical cover for company directors and employees, from small teams to growing businesses. Your team could get treated sooner and back to work faster, and staff often value it as a benefit. Cover and costs depend on the provider and your business.

Do you arrange buildings and contents insurance?

Yes. We can arrange buildings insurance, which covers the structure of your home and is usually a condition of your mortgage, and contents insurance, which covers your belongings. If you're buying, your lender will usually need buildings insurance in place from exchange of contracts.

Book a free call

Let's talk about your plans.

Choose who you'd like to speak to, then pick a time that suits you. We'll call at the time you book, listen to what you need and talk you through your options.

  • Completely free, with no obligation
  • Speak to Lois or Harry directly, not a call centre
  • Advising clients in Suffolk, Essex and across the UK
Who would you like to speak to?

Prefer to talk now? Call 01787 209880 or email [email protected]

Loading the booking calendar… Or book directly with Lois or Harry

Ready to take the next step?

Book a free, no-obligation call with Lois or Harry and find out what's possible for you.